Common Mistakes Startups Make with Angel Investors (And How to Avoid Them)
Raising too early, mixed terms, no lead investor, SEIS and EIS left too late, no shareholders' agreement, money people cannot afford to lose and going quiet after the round.

Leila raised £180,000 for her food-waste app in Bristol from nine angel investors. It felt like a triumph. Six months later it felt like a headache: three different sets of terms, two investors who could not claim the tax relief they had been promised, one uncle who rang every week about “his money”, and a cap table her next investor described as a mess. None of it was dishonest. It was just rushed. Most mistakes with angel investors are like that: small shortcuts early on that become expensive later.
| Common mistake | Better approach |
|---|---|
| Raising with nothing to show | Get evidence first: users, sales, pilots |
| Different terms for different angels | One round, one set of documents |
| No lead investor | Find one experienced angel to set terms |
| SEIS/EIS left too late | Get HMRC advance assurance before raising |
| No shareholders’ agreement | Agree the rules before the money lands |
| Going quiet afterwards | Short, regular, honest updates |
Raising before there is anything to back
Image source: pexels.com
Angels back people, but they also want evidence. The market is tighter than it was. The British Business Bank’s 2026 equity tracker found smaller UK businesses raised £12.3 billion across 2,002 deals in 2025, with deal numbers down 17% and seed deals down 27%. When money is scarcer, investors are pickier about what they see. Pitching with just an idea usually means a lower valuation, or no deal at all. Leila’s strongest meeting came after she had three supermarkets trialling the app. If you are not sure what investors look for, our guide to how angel investors evaluate startup ideas explains it, and a clear business plan for funding shows you have done the thinking.
Different terms for different people
Image source: pexels.com
Leila’s first angel got shares at one price, the next two invested through a convertible loan with a discount, and the rest came in later at a higher valuation with different rights. Each deal made sense on the day. Together they confused everyone and took weeks of legal time to untangle before her next round. Run a round as one event: one valuation or one set of conversion terms, one set of documents and a closing date. If you use convertible instruments, understand how they turn into shares first; our guide to convertible loan notes walks through it, and cap table basics shows how each choice affects who owns what.
No lead investor, and too many tiny cheques
Image source: pexels.com
A round without a lead drifts. Everyone waits for someone else to commit, nobody negotiates the terms properly and the founder spends months chasing small amounts. A lead angel, usually someone experienced who puts in a meaningful sum, sets the terms, reviews the documents and gives others the confidence to follow. Very small cheques cause a different problem: every shareholder needs paperwork, updates and signatures for future decisions. Twenty investors at £5,000 each is far more work than four at £25,000. Some founders solve this with an angel syndicate or a single nominee structure. Our guide to angel investment rounds covers how rounds are usually put together.
Leaving SEIS and EIS too late
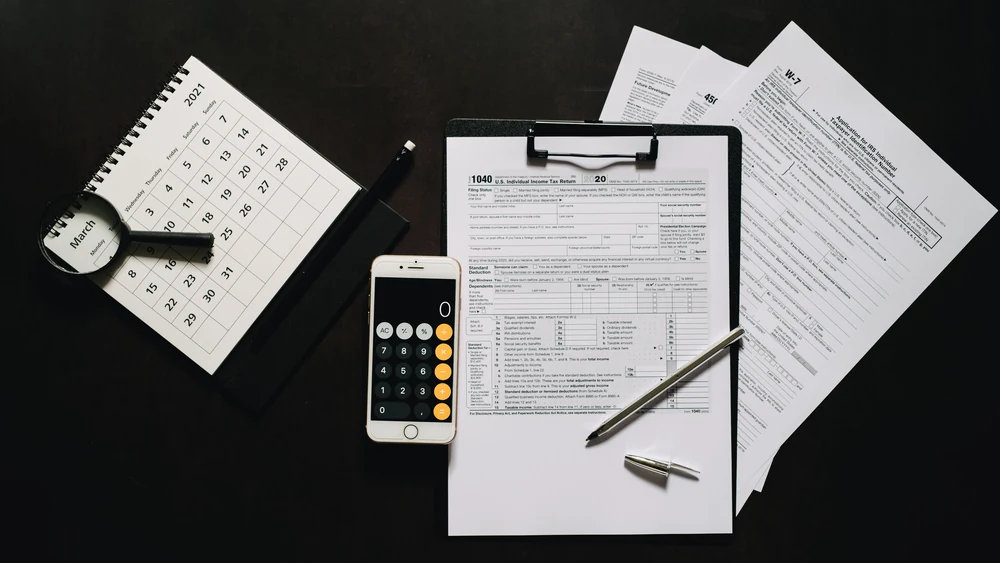
Image source: pexels.com
Most UK angels expect tax relief. Under SEIS, a young company can raise up to £250,000 and investors can claim 50% income tax relief. EIS gives 30% relief, and from April 2026 the limits doubled: most companies can now raise £10 million a year and £24 million in total. But the rules are strict, and one wrong step can cost investors their relief. Share rights, how the money is used and even the order of share issues all matter. Apply to HMRC for advance assurance before you start raising; most serious angels will ask for it. Two of Leila’s investors lost SEIS because shares were issued before the paperwork was right. That cost them real money, and cost her goodwill.
Skipping the shareholders’ agreement
Image source: pexels.com
Once angels hold shares, you need clear rules on what happens next. A shareholders’ agreement and updated articles should cover who can sell shares and to whom, what happens if a founder leaves, what decisions need investor approval, and how future rounds work. Without them, one unhappy shareholder can block a sale or a new investment. Be careful with board seats too. Offering one casually to secure a cheque can leave you with a board that is hard to change. An investor observer or a regular advisory call often gives experienced angels the involvement they want without the formal power. Pay for a solicitor who knows startup deals; it is cheaper than fixing it later.
Taking money people cannot afford to lose
Image source: pexels.com
Most startups fail, and angel investments are often lost entirely. That is fine for experienced investors who spread their money across many companies. It is not fine for a relative using their savings. Leila’s uncle put in £15,000 he could not really spare, and every bad month became a family conversation. Only take money from people who understand the risk and could lose it without real hardship. Promoting shares is also regulated: most angel rounds rely on exemptions for high net worth or sophisticated investors, which require the right statements to be signed. Ask your solicitor to check this before you send a pitch deck to anyone outside that circle.
Over-promising in the pitch
Enthusiasm is expected. Invented numbers are not. Hockey-stick forecasts with no basis, customer names you do not really have, or “talks” with big companies that were one email exchange all come back to bite you. Investors compare what you said with what happened, and trust drops fast when the gap is large. At its worst, knowingly or recklessly making misleading statements to get someone to invest can be a criminal offence. Be ambitious but honest: show your assumptions, explain the risks you see and what you will do about them. Experienced angels trust founders who can name their own weak spots far more than those who claim to have none. Our overview of angel investors explains what they expect in return.
Choosing investors by cheque size alone
The biggest cheque is not always the best one. An angel who knows your industry, opens doors to customers and stays calm when things go wrong is worth more than one who invests more but calls in a panic every month. Do your own checks. Ask to speak to other founders they have backed, especially ones whose companies struggled. Ask how often they expect updates, what they will help with, and whether they can invest again in future rounds. Leila learned that her quietest investor, a retired food retailer, was the most useful: two introductions from him led to her first paying supermarket contract.
Going quiet after the money lands
Image source: pexels.com
The most common mistake happens after the round closes. Founders get busy and investors hear nothing for months, so they assume the worst. Send a short update every month or quarter: key numbers, what went well, what did not, cash left and how long it will last, and one or two specific ways investors can help. Be honest about bad news; angels forgive setbacks far more readily than silence. Knowing your runway and burn rate makes these updates easy to write, and it means you will start raising again before the money runs low, not after.
How Leila’s second round went
For her second raise, Leila had HMRC advance assurance in hand before the first meeting. A former retail director agreed to lead, set the terms and brought four other angels with him, all on one set of documents. A proper shareholders’ agreement was signed on day one, and every investor got a one-page update on the first Monday of each month. The round closed in ten weeks instead of seven months. Avoiding mistakes with angel investors is not about being perfect. It is about slowing down enough to get the basics right before the money arrives.
Frequently asked questions
What is the biggest mistake startups make with angel investors?
Raising before they have evidence such as users, sales or pilots, then accepting poor terms or a messy round because they need the money.
Should I get SEIS advance assurance before raising?
Yes. It is optional, but most UK angels expect it, and getting it first reduces the risk of investors losing their tax relief.
How much can a company raise under SEIS?
Up to £250,000 in total. Investors can claim 50% income tax relief on SEIS investments of up to £200,000 a year.
Do I need a lead angel investor?
It helps a lot. A lead sets the terms, reviews documents and gives other investors confidence, so the round closes faster.
Should I take investment from friends and family?
Only from people who understand the risk and could lose the money without hardship. Get advice on financial promotion rules first.
How often should I update angel investors?
Monthly or quarterly. Share key numbers, cash runway, wins, problems and specific ways investors can help. Silence damages trust.
This article is general information, not legal, tax or investment advice. SEIS and EIS rules are strict and change over time, and promoting shares is regulated. Take advice from a solicitor and accountant before raising investment.



