Angel Investors vs Venture Capital: Key Differences
Angel Investors vs Venture Capital: Learn the key differences in funding stages, investment size, risks, and how to choose the right option for your startup.

Venture capital funding and money from angel investors both buy equity, and founders often treat them as the same thing at different scales. They are not. Who the money belongs to, who decides, and what each party needs from the outcome are all different, and those differences shape the entire relationship.
Whose Money It Is
An angel invests their own money and answers to nobody. A venture fund invests money raised from other institutions and individuals, and it has legal obligations to them. This single distinction explains most of the differences that follow — a fund is not free to be flexible in the way an individual is, because it is spending someone else’s money against a mandate.
How Decisions Get Made
Image source: pexels.com
An angel can commit over lunch. A fund typically requires the partner you met to build a case for colleagues at an investment committee, using material you supplied, with you absent. This is why angel rounds can close in weeks while institutional rounds routinely take months, and why written material matters more with a fund than a good meeting does.
Cheque Size and Stage
Angels generally invest earlier and smaller, often when there is little to analyse beyond the founders and the idea. Funds usually want evidence — customers, retention, some proof the thing works — before committing larger sums. Approaching a fund too early is one of the most common reasons founders collect rejections that say nothing about the business.
What Each Side Needs From the Outcome
A fund needs investments capable of returning a meaningful share of the entire fund, because most of its return comes from a small number of outcomes. A solid business with a moderate ceiling fails that test regardless of how well run it is. An angel can be perfectly satisfied with a smaller return, which makes them a better fit for companies that will be good rather than enormous.
Terms and Documentation
Angel investments are often made on lighter documentation, sometimes through convertible instruments that defer the valuation question. Institutional rounds bring fuller paperwork: liquidation preference, consent rights, board composition, anti-dilution and information rights. Neither is inherently better, but the institutional version permanently changes who controls decisions.
Involvement After the Money Arrives
Angels vary enormously. Some are genuinely useful and available; others invest and are never heard from again. Funds are more consistent — you will get board meetings, reporting requirements and a defined relationship — but that consistency includes obligations as well as support.
The UK Tax Position
British angel investing is shaped heavily by the government’s venture capital schemes, which give qualifying investors relief on early-stage investments. This is why UK angels ask about eligibility so early, and it is a meaningful part of why angel money is available at all at the earliest stage. Institutional funds are generally not investing for tax relief, so the question rarely arises with them.
Follow-On Capacity
Funds reserve capital to support companies through later rounds; most individual angels cannot. This matters more than it appears at the time. An investor unable to participate in the next round is visibly absent from it, and incoming investors read that absence as a signal whether or not one was intended. Ask any prospective lead how much they hold back for follow-on investment.
What Happens When Things Go Badly
This is the difference founders feel most and consider least. An angel risking their own money can decide to be patient, or to write it off gracefully. A fund has obligations to its own investors and a portfolio to manage, so its response to a struggling company is shaped by considerations that have nothing to do with you. Take references from founders whose companies did not work out — that is where this becomes visible.
They Are Usually Sequential, Not Alternatives
For most companies this is not a choice between two options. Angels fund the stage before there is enough evidence for a fund, and a well-run angel round is what makes an institutional round possible later. The practical question is which is appropriate now, and whether the terms you accept today will make the next raise easier or harder.
Choosing Between Them When You Genuinely Can
If both are available, weigh the speed and flexibility of angel money against the depth of capital and follow-on capacity of a fund. A fund that can support later rounds is worth something real. So is retaining control of your own company for another year. The answer depends on how much capital the business genuinely needs and how fast the market is moving.
Who Represents Each Side in the UK
Both sides of this market have national bodies, and knowing them shortens the search considerably. The UK Business Angels Association is the trade body for angel investing in Britain and lists networks and syndicates by region and sector. The British Private Equity & Venture Capital Association performs the equivalent function for venture capital and private equity firms, and its member directory can be filtered by the stage and sector a fund actually invests in.
Where the Institutional Money Originates
Venture funds raise capital from pension funds, insurers, university endowments, family offices and, in the UK, from the British Business Bank through its investment programmes. That last point explains a genuine feature of the British market: a meaningful share of venture capital available to UK companies traces back to government-backed programmes investing into funds rather than directly into companies.
SEIS, EIS and Advance Assurance
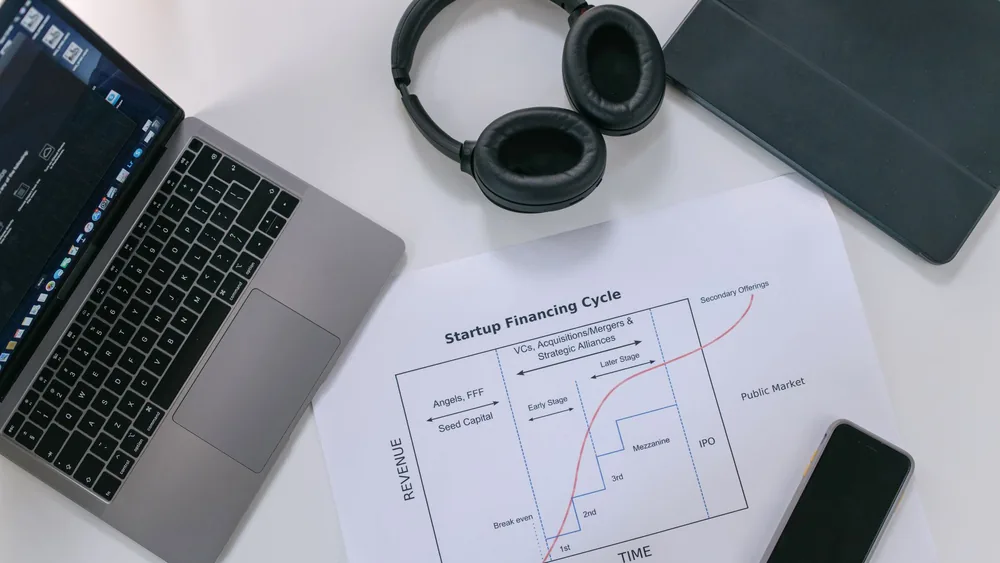
Image source: pexels.com
The government’s venture capital schemes — principally the Seed Enterprise Investment Scheme and the Enterprise Investment Scheme — shape angel behaviour more than any other single factor. Companies can apply to HMRC for advance assurance that a proposed share issue is likely to qualify, and many UK angels expect to see it before committing. Institutional funds generally are not investing for relief, so the question rarely arises with them.
Final Thoughts
Both angel investors and venture capital firms play vital roles in the startup funding ecosystem.
Angel investors help transform early ideas into viable businesses by providing initial capital, mentorship, and connections.
Venture capital firms then help successful startups scale rapidly by injecting larger amounts of funding.
For founders, understanding angel investors vs venture capital is not simply about comparing funding sources — it’s about choosing the right partner at the right stage of the startup journey.
In many cases, the most successful startups work with both.
Angel investors help startups take their first steps, and venture capital firms help them run much faster once momentum begins to build.
FAQs
1. What is the main difference between angel investors and venture capital?Angel investors are individuals investing personal money into early-stage startups, while venture capital firms invest pooled funds into high-growth businesses.
2. Do angel investors invest earlier than venture capital firms?Yes. Angel investors typically invest during pre-seed or seed stages, while venture capital firms usually invest at later stages.
3. How much do angel investors invest compared to venture capital firms?Angel investments often range from £10,000 to £250,000, while venture capital investments may start at several hundred thousand pounds and reach tens of millions.
4. Are angel investors easier to approach than venture capital firms?In many cases, yes. Angel investors may have a simpler decision-making process and may be more accessible through startup networks.
5. Can a startup have both angel investors and venture capital investors?Yes. Many startups raise angel funding first and later secure venture capital as the business grows.
Author Bio
Rajiv Gupta has more than 10 years of experience in digital media and online publishing. He runs Union Post, which covers UK business, finance and entertainment.
Disclaimer
This article is for informational purposes only and does not constitute financial, legal, or investment advice. Founders should consult qualified financial professionals before making funding decisions.



